Deposits next to the score
Recent revenue, existing payments, and time in business sit beside credit. A thin score with strong deposits is a different file from the reverse.
Operating businesses
Tell us what the company needs. We look at deposits, time in business, and the job the money has to do. A prequalification is a first look, not a credit decision.
Products
Five programs. The right one depends on whether revenue is steady, card sales swing, or the need is a specific asset.
A short-term amount against a steady deposit history, paid down on a fixed schedule.
See working capitalA slice of future card sales, remitted as those sales come in, for weeks that are not all the same size.
See cash advancesAvailability you draw when a cost shows up. You pay on what you actually use.
See lines of creditA machine, vehicle, or gear package on its own term, so operating cash is not the one paying the invoice in full.
See equipment fundingA longer note for a business that has already proved the model and has a project that should not be crushed into a few months.
See longer termsHow a file moves
Amount, product, revenue, and how to reach you. That first pass does not decide the rate.
If the file is complete, we aim to respond the same business day with the options that actually match.
After you accept written terms and any documents are in, funds are sent to the business bank account.
Why the file is wider than a score
Recent revenue, existing payments, and time in business sit beside credit. A thin score with strong deposits is a different file from the reverse.
You are not left to compare products alone. We say which structure fits the way money comes in, and which one would strain it.
Daily, weekly, or monthly, depending on the product. The total dollars are shown before anyone agrees.
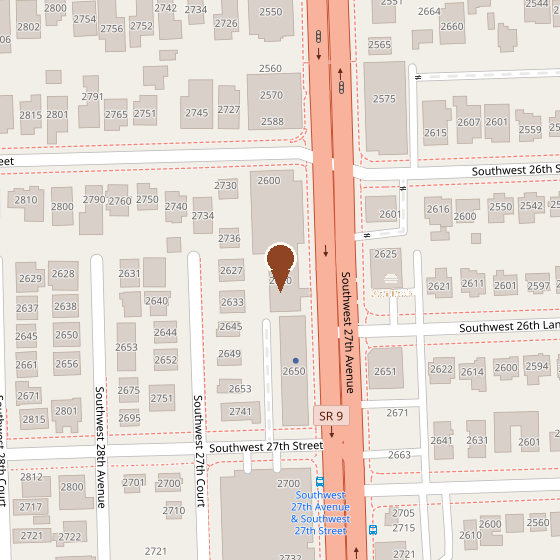
Office
2620 SW 27th Ave
Miami, FL 33133